What is the baseline market scope and valuation of the Alcohol E-Commerce Market?
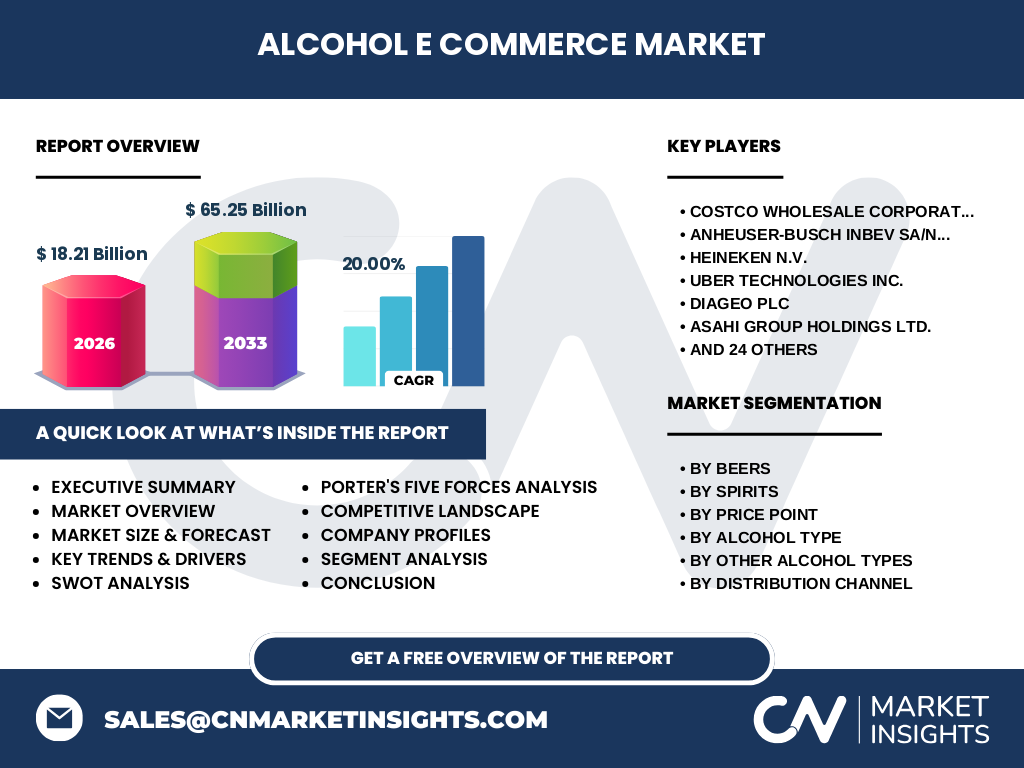
Our analysis indicates that the Alcohol E-Commerce Market size stands at 18.21 Billion in 2026. This valuation captures digital retail transactions across beers, spirits, and wines, reflecting massive shifts in consumer purchasing behavior toward online platforms.
Structural Growth Drivers and Restraints
The market is propelled by a robust 20.00% CAGR, driven by digital-first consumer habits. However, complex cross-border logistics and stringent regulatory hurdles enforced by bodies like the TTB in the US create entry barriers for emerging direct-to-consumer platforms.
Emerging Trends and Growth Patterns in the Alcohol E-Commerce Market
Consumer preference is heavily tilting toward premiumization within spirits and health-conscious alternatives. Platforms specializing in Ready-To-Drink Cocktails and craft iterations are capturing exponential wallet share, fueled by targeted social media marketing and seamless app-based checkouts.
How did COVID-19 permanently alter the digital alcohol landscape?
The pandemic acted as a massive catalyst, forcing archaic three-tier distribution models to rapidly digitize. Regulatory relaxations on curbside pickup and home delivery during lockdowns permanently accelerated baseline adoption rates across online alcohol marketplaces.
Competitive Benchmarking and Strategic Dynamics
The landscape features a blend of traditional beverage giants like Anheuser-Busch InBev SA/NV and tech-enabled disruptors. Companies increasingly leverage proprietary apps and strategic acquisitions to secure last-mile delivery superiority and capture lucrative first-party consumer data.
Executive Summary of the Alcohol E-Commerce Market Industry Trends
Our exhaustive Alcohol E-Commerce Market analysis projects an explosive expansion from 18.21 Billion to 65.25 Billion by 2033. This trajectory underscores a fundamental, irreversible migration of alcohol retail toward digital channels.
Market Forecast and Valuation Trajectory (2027 to 2033)
Driven by sustained 20.00% CAGR growth, the market will surge from its 2026 baseline to reach 65.25 Billion by 2033. This forecast reflects rising smartphone penetration and the scaling of specialized logistics networks handling fragile glassware and temperature-sensitive wines.
Segmentation Analysis of the Alcohol E-Commerce Market
The market breaks down by category: Beers (Craft, Lager, Ale, Stout and Porter, Cider), Spirits (Vodka, Whiskey, Rum, Gin, Tequila, Liqueurs), Price Point (Economy, Mid Range, Luxury), and Wines And Champagnes (Red, White, Rosé, Sparkling, Champagnes, Dessert). Alternative segments include Ready-To-Drink Cocktails, Sake, and Mead.
Geographic Distribution and Regional Performance
Regional performance varies widely based on localized licensing laws. North America leads adoption due to advanced online grocery infrastructure, while Europe shows strong momentum led by specialized DTC wine merchants navigating complex intra-EU excise tax regimes.
In-Depth Regional Review and Regulatory Constraints
State-by-state regulations in the United States and strict alcohol advertising laws in various European nations dictate regional expansion. Platforms must integrate advanced age-verification technology to comply with regional legal frameworks while scaling operations.
Strategic Positioning of Leading Industry Participants
Key players like Constellation Brands Inc. and Pernod Ricard SA invest heavily in DTC capabilities. Meanwhile, platforms like Wine.com LLC and ReserveBar Express Corp. dominate through curated selections and premium luxury positioning.
Porter's Five Forces Assessment
The threat of new entrants remains moderate due to steep regulatory licensing costs. Buyer power is high given intense price competition among online marketplaces, while supplier bargaining power is concentrated among global beverage conglomerates.
SWOT Analysis of the Alcohol E-Commerce Sector
Key strengths include unmatched consumer convenience and data analytics capabilities. Weaknesses involve high shipping costs and complex return logistics. Opportunities lie in emerging Ready-To-Drink Cocktails, while regulatory clampdowns represent persistent threats.
Value Chain Analysis from Raw Materials to End-Users
The value chain spans agricultural raw materials (grains, grapes), distilleries and breweries, tier-one distributors, and digital storefronts utilizing specialized fulfillment centers to execute compliant last-mile delivery to verified adult consumers.
Investment Insights and High-Potential Areas
Investors should target logistics technology startups solving age verification and cold-chain transport for fine wines. Premium spirits and artisanal Ready-To-Drink Cocktails offer the highest margin expansion opportunities through direct-to-consumer channels.
Conclusion and Strategic Takeaways for Stakeholders
Capturing value in this rapidly scaling market requires nimble regulatory compliance and robust digital marketing. Brands failing to establish a strong omnichannel presence risk losing direct consumer relationships to agile digital marketplaces.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with fulfillment executives, and secondary macroeconomic indicators from global beverage trade associations.
Scope of the Report and Analytical Limitations
This report covers global digital retail transactions for alcoholic beverages through 2033. Limitations include rapidly shifting state-level liquor legislation and unrecorded illicit peer-to-peer digital transactions excluded from official customs data.
Recent Developments and Strategic Industry Moves
Recent activity features aggressive digital acquisitions, such as major brewers buying DTC wine platforms, and technological rollouts featuring biometric age-verification at doorstep delivery to satisfy tightening regulatory standards across key metropolitan markets.